When people tell you how they sacrificed to get into the home that they bought in the ‘90s (and it’s been paid off forever), it’s hard to take their sacrifice seriously. The idea that skipping your daily takeaway coffee will make a big difference feels like it’s missing the point.
Of course everything is relative and every timeline has it’s own challenges, but right now is indisputably the hardest time to buy a home. If I were to have my time again - if I were 29 years old in this buying environment - this is what I would do:
I would look to buy a 2, ideally 3 bedroom townhouse in South East Queensland or Northern New South Wales for $775,000 (or any number under $800,000 - just using $775,000 as a reference point).
Why that TYPE OF PROPERTY?
The Queensland vs. New South Wales stamp duty situation is a factor. New South Wales first home buyer stamp duty concessions are a bit more attractive but there are fewer properties that fit that description under the $800,000 threshold. It would be challenging to take advantage of the concessions with far less choice.
South East Queensland seems to have a lot of those types of property. Since I work from home, I can be flexible on location.
Ideally 3 bedrooms would allow you to rent out a room (or 2) and get flatmates in to help pay your mortgage. Now at this stage some people will be a hard out on sharing their space, but if it’s a game-changer between getting in or not, then I’m doing it. Especially if you can chunk it down into 5 year compartments. Once I get over the hurdles of saving for a deposit, getting approved and finding a home, I’m going to rent out rooms, clobber my mortgage and re-assess in 5 years time.
At 29, I had no intention of having children. They were not factored into the equation anywhere, I think I assumed that we would be on to our second home by the time I was ready to be a mum, or that we would only have one child and it just wasn’t part of my reasoning then.
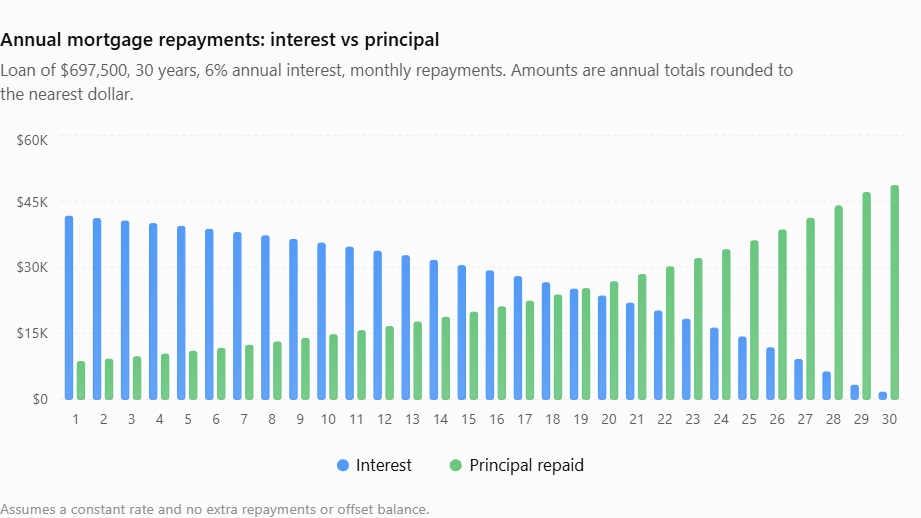
The mortgage repayment curve is real…you repay the lions share of the interest first!
WHY THOSE NUMBERS?
An established (not new) $775,000 property in Queensland, for a first home buyer, will incur $15,520 worth of stamp duty ($5,205 first home buyer concession) - if the property is over $800,000 you don’t receive that concession at all.
Any $775,000 property (new or established) in New South Wales, for a first home buyer will incur $0 worth of stamp duty [I’m going to create a blog post on this exact topic because about a month ago, we did a pre-purchase inspection in Northern New South Wales that helped the buyer negotiate their purchase price to under $800,000 and it made a world of difference to her in stamp duty concessions]
If the property is brand new in Queensland you get 100% concession, no stamp duty at all, no matter what the cost of the property is.
With regards to the deposit - on a $775,000 mortgage - a 10% deposit is $77,500. Seems achievable.
First home buyers can dodge the mortgage insurance costs (federal scheme) without having to produce a 20% deposit for your mortgage which is good since a $155,000 deposit just doesn’t seem realistic. Lets just say for this exercise that you only have a 10% deposit.
That makes for a $697,500 base mortgage. Assume we get a rate of 6% the minimum repayments should be approximately $4,182 per month ($50,184 per year). That will take you 30 years to clear, however…
HOW THIS ALL SHAKES DOWN:
If you have an offset account that you tip all your money into, it will decrease your 30 years dramatically. Assume you put $500 extra of your own money in to offset monthly. Then you add $275 per week for the room rental. That will chop your mortgage length in half, to 15 years and 1 month.
WAIT A MINUTE I don’t want a flat mate for 15 years, what about the 5 year chunk???? OK yes, right, row that back. If you have a flat mate for just the first 5 years of your mortgage, you STILL decrease your mortgage time to 19 years instead of 30. Turns out the first 5-10 years of your mortgage is the most influential time to really clobber it, because that’s when the bulk of the interest is charged. Remember this: Banks get the bulk of their money first.
Because of the interest curve it’s not a great idea to refinance every 2 years. You never get past the crazy interest charges, so even if the rates rise you may not be doing the right thing by chopping and changing often as you will never make a substantial impact on the principal.
Obviously all the first home buyer schemes and interest rates can change at any time, but the basics remain the same. Know what you’re shooting for, have a plan for once you get your mortgage because the monthly repayments are savage, and make yourself a little road map for how to get there before you get started. Do your research - check online and also with a trusted conveyancer plus the most creative and dynamic mortgage broker you can find. Assemble your A Team.
BUYING SOON? START WITH THE PLAYBOOK
Our complete home buying system: ten step-by-step modules, from working out your budget through to settlement. $29, one-off, yours to keep.